

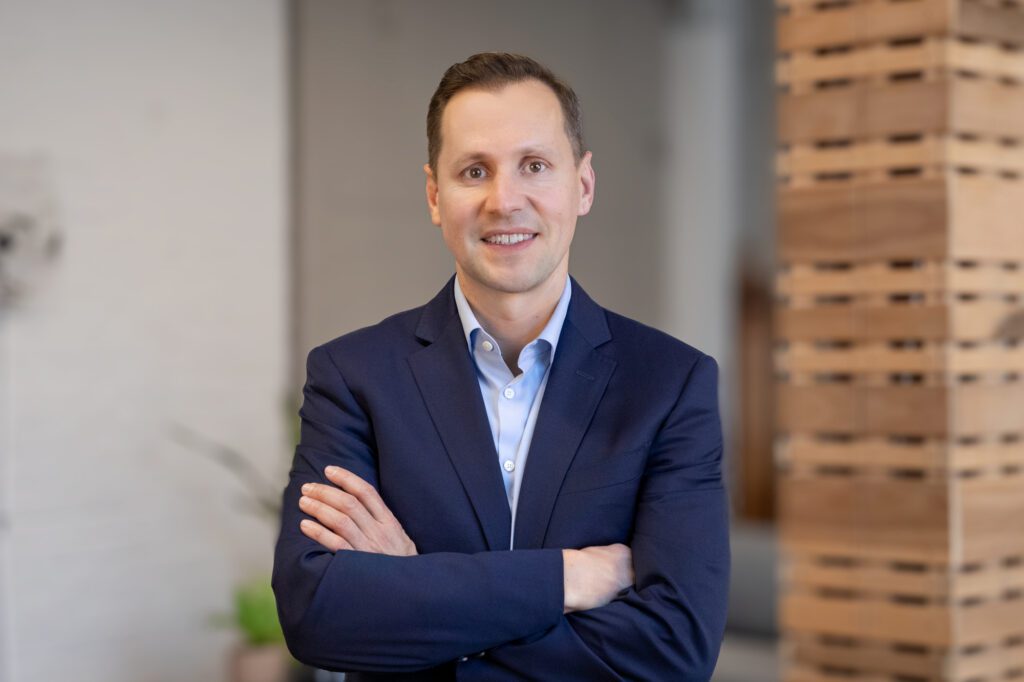
Peter Billmeyer, co-founder and CEO of Bespoke Commercial Real Estate, joins Craig Castelli to discuss how real estate decisions can shape a business and its eventual sale. They cover lease negotiations, personal guarantees, sale leasebacks, and the differences between owning and leasing a property. Peter also explains how real estate factors into private equity and strategic acquisitions, and why business owners should think about their space as part of their broader M&A strategy.
Exploring the Art & Science of dealmaking
Welcome to The Close M&A Podcast with Caber Hill Advisors, where we bring you exclusive insights from M&A experts, business owners, and industry leaders navigating the complexities of buying and selling businesses. Hosted by Craig Castelli, this podcast demystifies the dealmaking process, shares success stories, and offers invaluable lessons for business owners and investors.
Craig Castelli, Founder & CEO of Caber Hill Advisors, is a trusted M&A expert with decades of experience advising business owners through successful transitions. Alongside a rotating roster of advisors, entrepreneurs, and investors, Craig brings engaging conversations that illuminate the world of middle-market M&A.
- ABOUT THE EPISODE
-

Peter Billmeyer, co-founder and CEO of Bespoke Commercial Real Estate, joins Craig Castelli to discuss how real estate decisions can shape a business and its eventual sale. They cover lease negotiations, personal guarantees, sale leasebacks, and the differences between owning and leasing a property. Peter also explains how real estate factors into private equity and strategic acquisitions, and why business owners should think about their space as part of their broader M&A strategy.
- SUBSCRIBE
-
- ABOUT THE PODCAST
-
Exploring the Art & Science of dealmaking
Welcome to The Close M&A Podcast with Caber Hill Advisors, where we bring you exclusive insights from M&A experts, business owners, and industry leaders navigating the complexities of buying and selling businesses. Hosted by Craig Castelli, this podcast demystifies the dealmaking process, shares success stories, and offers invaluable lessons for business owners and investors.
- ABOUT THE HOST
-
Craig Castelli, Founder & CEO of Caber Hill Advisors, is a trusted M&A expert with decades of experience advising business owners through successful transitions. Alongside a rotating roster of advisors, entrepreneurs, and investors, Craig brings engaging conversations that illuminate the world of middle-market M&A.
- BE OUR NEXT GUEST
-
LISTEN
WATCH
READ
Craig Castelli:
Welcome to The Close M&A Podcast with Caber Hill Advisors. I’m your host, Craig Castelli, and today my guest is Peter Billmeyer. Peter is co-founder of Bespoke Commercial Real Estate, a boutique real estate firm headquartered here in Chicago. If you can see the sky behind him, we have a nice storm rolling in today, so we’re wondering if this will be episode number one of being interrupted by a tornado, which probably feels right at home for you being from Omaha, I would imagine.
Peter Billmeyer:
It’s fair. It’s fair. Definitely brings back some childhood memories of running into the basement.
Craig Castelli:
So let’s jump right in. You founded Bespoke in 2013. Tell us, what was the idea and why’d you think it would work?
Peter Billmeyer:
It’s one of my most favorite stories I have. So my partner and I had had a decent run at a previous company, and he’s the son of a Colombian immigrant entrepreneur. I’m the son of a female entrepreneur. And while I was sitting with the chairman of our current board in a mountain town on vacation, we just kind of whiteboarded this thing out verbally over a few cigars and recognized that there were so many amazing tenant-specific firms that had all been acquired. So there was a market opportunity. And if you’re looking at your go-to-market, we figured out that our most passionate deals and our closest relationships were those where they were privately held and owned by entrepreneurs. And so that’s what we kind of built the construct around, and it’s just been off to the races ever since.
Craig Castelli:
It seems like you’ve held true to that construct and avoided the temptation to start chasing the massive headquarters. Is that a fair statement?
Peter Billmeyer:
It’s a painful statement. I think anybody that’s a business major understands that TAM is extremely important, but I kind of figured out early in my career, the ability to get the meeting, to go pitch and try to win business, while that feels great, when you’re kind of outgunned or you can only win five to 10%, it’s a good way to go broke. And so we’ve been extremely committed to that strategy. We don’t do retail, we don’t do anything landlord, we don’t do anything publicly traded, and we do a small amount of nonprofit just because those are labors of love and I think they’re so important. But office and industrial, privately held, that’s our whole life.
Craig Castelli:
Yeah. I mean, we take a similar approach. If you look at the deal size that we focus on in the lower middle market, it’s not because we can’t do a bigger deal, but if you just think about the dynamics of the market and where we are most likely to win at the end of the day, you and I are both running businesses here. That really has to be a factor in what you’re chasing instead of just pursuing what might be a sexy, shiny new object.
Peter Billmeyer:
Yeah. I mean, jack of all trades, master of nothing is just brutal. And we’ll see competitors or see other firms, whether local or across the country, and I had been in that environment. I think there’s such great synergy between our respective firms because how do you not get fired up? How do you not fight for that extra half turn on EBITDA or whatever in your world when it’s your client’s money? It’s their legacy, it’s their family’s wealth. It’s even the private equity investors. It’s pretty easy to be motivated and stay in the fight, if you will, when you know how much it materially matters to your client.
Craig Castelli:
Well, the impact on an entrepreneur is just disproportionately greater than a big corporation, a big investment fund, some other institution like that, whether it’s what you do or what I do. I mean, it’s just monumentally more impactful if we do our job the right way.
Peter Billmeyer:
Unequivocally. Couldn’t agree more.
Craig Castelli:
So does that play into why you guys don’t work for landlords either and really only support tenants?
Peter Billmeyer:
Yeah. So it’s simple. I’m sitting in a half-a-million-square-foot building, and if you do both sides, it just always comes down to who’s the client. And you never want to say anything disparaging about the big firms and how there are brokers that specifically and exclusively only do one side or the other. And it’s an ecosystem, so we respect them, we work with them, but ultimately there can only be one client. And if you’re a 10,000-foot investment bank or 15,000-foot accounting firm in a half-a-million-square-foot building, that bigger organization, that bigger company is going to want to cater toward the landlord, whether they’re on this current building or something else across the portfolio. I mean, that’s really just how it goes down. And sadly, it’s not really the broker’s fault. If you look at a JD, or Juris Doctor degree, you conflict out, right? You can’t have lawyers in the same firm working both sides of a case. Our industry should be fiduciaries. We should be held to a higher standard. Our license is the exact same as residential. I think we can agree that dollars and cents are historically quite a bit different. And so for us, it’s the only way that we think that we can do business in the proper manner.
Craig Castelli:
Yeah, no, that makes a lot of sense. And I think, well, I know I’ve heard you tell stories anecdotally at least about putting money in the pockets of your clients, how you’ve helped them out of a situation and saved them a six-figure amount or structured a new lease a certain way. And I don’t think the average person naturally thinks of a lease that way. If I think about making a hundred grand on a real estate deal, I think I bought low and I sold high and it’s your typical investment, but you’re doing this with leases. So I would love to talk about that a bit because even I don’t fully appreciate it. I bet you the average listener doesn’t either.
Peter Billmeyer:
So I want to bifurcate this answer because there’s two really interesting sides to this. First and foremost, one of the coolest things about Chicago on the office side is we’re very, very unique across the country in that the commissions are set and it’s not proportionate to what your client is paying. So even at 70 bucks a foot for Class A and above, and then you get down into the $40s, the commission’s the exact same and it’s the square feet times the commission times the term of the lease. So we have all the incentive in the world, because of our model and never having landlords as clients, to get the most aggressive terms possible. And that’s the fun part. But what’s super interesting in the timing of our interaction, there is what I consider a wonderfully written article in Crain’s that just came out this morning, and it’s about a lot of this adaptive reuse. We’re seeing it all across the country, but in Chicagoland in particular, you’re seeing a lot of suburban stuff being converted into self-storage, being converted and torn down into retail. In the city, it’s being converted into multifamily. We have negotiated more buyouts where the landlord has to figure out how to incentivize our client to terminate the lease early than almost any other period in our careers combined. And it’s amazing. If you have great partnership, great counsel and a great broker working on your behalf, to see a 6,000-square-foot tenant get a couple, three, 400 grand, that’s material. And we understand we can underwrite the deal from a development standpoint, what the land acquisition cost was, and figure out what is the maximum pain point that that developer is going to swallow and endure to be able to move forward with the project. And by not being developers, that’s just us being fiduciaries on behalf of our clients.
Craig Castelli:
Right. Do you think this adaptive reuse trend is here to stay?
Peter Billmeyer:
Wow, what a great question. I think it’s a moment in time. I think it’s wonderful for the city if we can execute. I know some of the parties. I have a lot of respect for them. I think it’s no surprise that we have a massive housing shortage. We rank, I think, in certainly the bottom third to bottom fourth of the country for new homes and new apartments being built. And I think there’s so many buildings that are outdated where you would never want to office, I would never want to office. And if you’re a leader, you extrapolate that a layer down. How can you try to get your team back into the office if it’s dark, old, dilapidated? And so breathing new life into not only the building, but the ecosystem of the community, I think is a wonderful win for Chicago. And then you have the added benefit, and I know there’s some controversy around this, but a vacant building is not great for the tax roll. So spending millions and millions of dollars to convert it into, yes, residential is taxed at a lower tax rate than commercial, but in this instance, I think this is apartments, multifamily, commercial assets, this is a huge win. I just take my hat off to these developers that are really taking a lot of risk to help get Chicago back to the vibrant, safe city that we used to love.
Craig Castelli:
Yeah, I think that makes a lot of sense. I mean, one, you’re spot on about the housing shortage. Two, an office building that sits vacant for too long becomes a building that is not actually, or a building with an owner that probably is walking away from that tax bill at a certain point. So even if the tax base is lower in residential, it’s bigger than zero.
Peter Billmeyer:
Yeah. I mean, ultimately, whoever the lender is is going to have to make that up. Currently going through that in our building right now where it went back to the lender, but it’s just nasty. It’s a vicious cycle and for far too long, there’s an old term, but Chicago is kind of redlined for the last four to five years, six years from outside institutional investors. Hopefully with some change in leadership that we have coming this fall, we’re going to get off the timeout block. Right now we’ve got predominantly very entrepreneurial money coming in that’s private because that’s the only ones that are willing to take the risk.
Craig Castelli:
Yeah. What about some of this conversion to data centers? You mentioned the Crain’s article, which I have flagged in my inbox right now to still read that came out today about the residential conversion. But there was one a couple days ago about plans for, I believe, it’s in the West Loop or that tweener neighborhood between the Loop and the West Loop, they want to convert to a data center. Same argument prevails. Nobody’s going to put the money in the building to turn it into the office space it would need to be. And the pitch is that the data center is the perfect use. That’s another very controversial topic it seems these days.
Peter Billmeyer:
It is controversial, but I think it’s inevitable. It is here to stay. I think that obviously the number one issue for data centers before some of this public pushback was power. I think it’s truly incredible that organizations are willing to spend billions and billions of dollars into these CapEx projects. You look at the jobs, you look at the construction jobs that are created. If we are entering this “tool belt generation,” I think it’s wonderful in that regard. Now, I do agree that these aren’t permanent jobs that are created in heavy density, but it’s going to happen one way or another. I don’t think any of us would like to see China jump ahead and take the lead on AI. And so for me, I think I come back, my mom was born and raised on a farm in Iowa, and things changed. There was massive disruption with mechanization of farm equipment. And now I look at it, okay, I’m not smart enough, clearly, to project the future of where the new jobs, the new companies, the new opportunities are going to come from, but I’m excited. I’m optimistic. And a large part of my revenue, let’s call it 50%, is tied directly to office utilization. And I think it’s going to be a whole new world, and I’ve seen how it’s impacted our company directly, and I choose to take the optimistic side of that.
Craig Castelli:
Yeah. We’re past the point of putting your head in the sand and ignoring the reality, right? You can argue about where data centers belong, you can argue about the ethics and the efficacy, but this is something that is going to be a new reality for all of us. We can learn it, we can embrace it, and we can figure out where it fits in our lives, or we probably get left behind.
Peter Billmeyer:
Couldn’t agree more.
Craig Castelli:
So I want to touch on something else you said, just talking about the reuse, how you or I wouldn’t put our teams in some of these old buildings. And I think I saw you were quoted, or maybe it was an article you guys put out, I can’t remember, where you talk about just using your office space as a recruiting strategy. Talk about that and tailor it to your client base in mind. We’re not the tech companies that have raised hundreds of millions of dollars who can splurge on these Silicon Valley mega centers, but I’m assuming there are still certain things that we can do that make us stand out from the crowd.
Peter Billmeyer:
So our tagline, trademarked, is “real estate’s your down payment on culture.” I couldn’t believe more strongly in this. Investing in your space, I think, is one of the single greatest decisions that an entrepreneur can make. I think the table stakes is the culture piece and then it does bleed into the recruitment. If I look at our team, these are 100% commission, non-benefits-receiving kind of killers, and to get that level of talent, ex-Division I, Division III athletes and extremely smart, highly motivated, there has to be some type of trade-off. And so that, for the recruitment piece, is really important. I think you can do it in a judicious manner where you don’t break the bank. And to your point, we are not publicly traded, we’ve not done these big Series A, Series B raises and those types of things. It’s being very economical with your money. It’s where do you put it? And we always believe you put it in the heartbeat of the space, which is your common areas, having an awesome, amazing open kitchen, and that’s where you drive culture. But while a lot of brokers are proficient at that discussion, when you run your own P&L and you sign your own rent check, there’s a whole other layer and level that I think is even more important, and that’s the productivity layer. When I look at our team, and they all agree, they set their hours, but when I look at them at 5:30, six o’clock and they’re still here, or they go and they pour a beer from the bar and they come and they sit at their cube and they do that extra 30, 45 minutes of minutiae, not only are they getting ahead for tomorrow and being productive, but there’s also those magical conversations between teammates and employees. “Hey, Craig, I know your dad’s been not doing well. Any updates?” When you’re in the heat of the day, those don’t tend to happen as much, but I just am fully convinced that when you invest in your space and you put the time to do it right, it’s going to pay so many more dividends than just being your third-highest expense.
Craig Castelli:
So if I call you up later this year and I say, “Hey Pete, we have a year left. We’re starting to think about our next move.” I’m assuming you’re not just immediately saying, “Oh, what’s the square footage? Let me show you some space.” What are the questions that you need answered about me, my team, my goals before you can even start to think about the building, the square footage, the specific space?
Peter Billmeyer:
So that’s what’s so much fun. We got to learn exactly who Caber Hill is. We got to come in. Who are the key decision makers? What are we trying to achieve? What does the next five, seven, 10 years of the business look like, and what is that ideal blue-chip demographic makeup of your team? I can go into so many details about all that, which I know we don’t have time for, but my whole thing is until I understand who you’re trying to recruit, retain and build your team around, we can’t do a great job. Until I understand if you want to own this business for another five years, you want to own it for another 10 years, disposition of a business in your world, we’ve talked about this, it has completely different implications. If you’re selling to a strategic, your real estate more often than not can end up being a liability. Now, if you’re selling to private equity, your real estate can be an asset. So there’s all these different factors. We start at a very high level and then we distill that down to your custom real estate strategy. And we work with architects and programmers to figure out what the target space requirement is with a bit of a, let’s call it a 10 to 15% deviation. And then we get out and look at space. But in the end, if we did our jobs as close to perfect as possible, we have thought through all the building blocks that are going to set the foundation for Caber Hill 3.0, 4.0, wherever you’re at in your iteration of building your business. And I will tell you, it is the greatest darn feeling three, four months after putting a client in a new space and they just tell you, “I believed you, but I kind of didn’t, and this has been the greatest next iteration for our business. And I just see the joy on our team’s face and how much it’s elevated the organization.” And it’s like, how do you not get fired up about that? It’s just such a huge impact.
Craig Castelli:
Well, it’s always a little bit of a leap of faith, right? You’re signing up for five or 10 years, you’re probably personally guaranteed it. You have, as an entrepreneur, all the optimism in the world, but also all the anxiety in the world. I know you’re going through some of this right now as you guys are navigating what to do in your own office space, which is sick, by the way, and anybody who has a chance to go by and see it should do it. You definitely practice what you preach.
Peter Billmeyer:
I appreciate that. Yeah, we did a one-year renewal. We’re not happy with the market. There’s so much of this market. There’s an incredible CMBS article that just came out yesterday where the three-year party of “extend and pretend” is over. And the billions and billions and billions of dollars that are all coming due in the next 12 months in the CMBS, we’re upwards of 65 billion, is profound, and now we’re ripping the Band-Aid off. So let’s get these buildings back to the lenders in receivership, deed in lieu of foreclosure with a lower basis, new owners that want to come in and revitalize. Some of them want to come in and they want to convert them, but we want to get the ecosystem and the health back, and that’s super important. And for us, we’re kind of taking that wait-and-see approach. We need to expand. We actually had two interns leave a week early because we had some great new talent coming in. But one little quick kind of caveat, quip for all those fellow business owners, we will do every single thing in our power to never have a client personally guarantee a lease. There’s a number of reasons why. If you have any type of healthy banking relationship, you can put a simple letter of credit on your revolver if you don’t want to put up cash or any type of collateral for that. It’s very, very inexpensive. It’s the most simple way to protect your business in the event of anything tragic, in the event of a key man instance. And it’s renewed every year. The lenders love it, the landlords love it. And for me, we found that to be the most protective position that we can provide for our clients.
Craig Castelli:
So if it’s that available, why doesn’t every broker tell their client they should do that?
Peter Billmeyer:
Because it’s a lot more work to negotiate.
Craig Castelli:
Fair point. No further questions, Your Honor.
Peter Billmeyer:
Yeah, exactly. I mean, when you start getting into the tertiary layers of, and maybe this is a secondary, everybody wants to negotiate the amount of the security deposit, but that tertiary is the structure and how you go about doing it. It just takes that extra effort. It’s no different than negotiating your tail off to get the termination penalty down as low as possible on a unilateral option for your client, which is so valuable and can be the difference. In your world, having a great termination, when you’re going to sell a business on behalf of your client and they have a great termination and the acquirer doesn’t need that real estate, that could be a full turn on EBITDA where they’re able to walk away with clarity from that real estate situation versus a sublease. I mean, it’s material for that five to 7% when it actually is needed, but otherwise it’s kind of by the wayside and it’s pretty easy to just let it go because there’s not that level of sophistication on the business owner. You just don’t do it very often.
Craig Castelli:
Right, right. No, that makes perfect sense. So let’s transition to some M&A talk here a little bit. I’ll get fired if we don’t talk M&A for at least a couple questions.
Peter Billmeyer:
My favorite thing ever.
Craig Castelli:
I know it is. I know it is. So let’s key in on your prior comment. Real estate can be a liability when selling to a strategic, but an asset when selling to PE. Talk about how you view the world through that lens.
Peter Billmeyer:
Ultimately for us, it just comes down to there’s a ticking clock, and that’s in the private equity world. Strategics don’t tend to have the same time constraints. The LPs, if you go strategic, family office, it’s usually much more patient capital, and it allows those leadership teams and the boards to make what they would consider the very best long-term decisions that there is for the business. Private equity is a different animal. You invest in a fund, you have a timeline horizon that’s an expectation. You’re going to load up a lot of debt. You’re going to try to really, really grow top line, but certainly bottom line, you’re going to bring those efficiencies. So they’re just completely different animals and you got to know them both. We’re investors in both. We respect both. We think you have to have both, and even all three. Family office, I think, plays such an amazing role in this world and ecosystem too. But really knowing that, and after spending the time that we have and being active investors ourselves in pure businesses, never in real estate or never in office and in those types of environments, it’s a completely different skill set to really understand. And that’s where we work so well with advisors and teams like yourselves because we can have aligned interests. Yes, we’ll make your life a little bit more painful when maybe negotiating that sale leaseback or something like that, but it really does allow both organizations to put the client first.
Craig Castelli:
So I had sale leaseback on my topic list for today. So let’s talk about that a little bit because I’ve seen it, as a guy who knows very little about real estate, I’ve seen it as a powerful tool, but I’ve also seen where business owners can get burned if they structure them the wrong way. So I’d love for you to talk about pros and cons and maybe some of the gotchas there.
Peter Billmeyer:
So, I mean, ultimately there’s a couple factors because sale leaseback can mean a couple different things. One, you’re a healthy organization, you’re in need of capital. You own your building, you recognize that the market’s frothy. And so ultimately we just distill it down to cost of capital. If you sell this asset, you’re doing it because you’re going to want to bring in that capital into the business and there’s hopefully going to be a much higher ROI and ROC, if you will. So that can and can’t make sense. It depends. Where we see the biggest issues is on the disposition of the business where the owner still owns the real estate. And so often that lease gets negotiated to 10% of what it should be because it just adds friction to the deal. And I will tell you personally, I had to get involved after the fact with my father-in-law when he sold his business. I was not involved at all. But then when the lease came up for renewal, strategic owner, I was like, “Whoa, whoa, whoa. There’s some really important clauses that were just completely missed.” And so it’s taken us two different deal cycles to get the lease into a healthy place. But what’s so awesome about the organization and structure there is now this is an amazing annuity. You have no debt and this thing just rolls monthly. You set it up as a great triple net so that the tenant’s responsible for the maintenance and all those different pieces. So there’s not one answer. There’s not one strategy that’s better. It just takes the time and the intellect and the experience to actually try to figure out what is important to the seller, the owner, and then you create that custom strategy for them because everybody’s different. Some people want max dollars. I mean, think about how when you negotiate your deals, you can talk about that. Some people want as much upfront cash and they want as short of an earnout. Some people are afraid to be retired and be home and they want longer and they want more stock. They want the second bite. It’s all the same things. It just requires care and sophistication.
Craig Castelli:
Right. Well, even in our deals, there are two deals that can look identical on paper, same price, same 80% cash, 20% equity rollover. The way the equity is structured alone can be vastly different between the two transactions, and that can make all the difference in the world as to whether you’re getting a return or even seeing that extra 20% or not. And that’s just one of a number of things that we go through.
Peter Billmeyer:
Couldn’t agree more.
Craig Castelli:
We see this probably most commonly in the healthcare side of our business. I think with some of our industrial clients, there’s a little more appetite amongst the buyers to buy the real estate with the business should the owner want that. In healthcare, generally speaking, a lot of these funds, they’re raising money saying they’re not going to own real estate. They refuse to buy the real estate. So a doctor selling a practice has a choice. I can play landlord to this PE firm that now owns my business, or we’ve seen the emergence of all of these REITs who are investing in medical real estate and are talking about these turnkey solutions they have for both sides in that situation. I think I know enough about the nuance of this to put my foot in my mouth, but I’d be curious because I’ve fielded calls from time to time: “Hey, I can get a lot more if I sign a 20-year lease and I’m going to sell the business in two years.” And my question is, “Well, who’s going to assume your lease with 18 years left on it?” I’m assuming there are certain things that are presented to one side or the other as being very attractive that can actually be a deal killer on the M&A side.
Peter Billmeyer:
Yeah. So let’s just take that example you brought up. You look at all the roll-ups, pick any. My brother’s a surgeon. My brother sold his practice to private equity, so we’ll get to that next. But dental roll-up, dermatology roll-up, whatever. We’ll pick on Michigan Avenue. If I’m coming to buy your practice and I am seven blocks north, and I have an amazing facility built out, room to absorb your clientele, and you have 18 years left on your lease, what is your practice worth? I’m not going to be exposed to that risk of buying your practice and then having to sublease it where I get my face ripped off. That’s the exact scenario where, with a strategic buyer, real estate can be a liability. So yes, you can get an amazing deal, but there’s also cost of capital. You do a longer-term deal, the landlord kicks in more money, and it’s all part of those discussions. That’s why I mentioned earlier, we start our strategic discussions: What are your future plans for the business? Because if you have any type of disposition coming up, we have to understand that and the nuance of it. Now you’re a young guy, I’m a young guy. I think you love what you do. I know the value that you bring. So if you’re like, “Look, I want to run this at least for another 10 years, I got a great team,” then that kind of frees us up quite a bit. So those parts are what are really fun, and that’s the strategic side of understanding business and not just real estate and trying to get the best deal possible. Because there’s such an amazing line I learned early in my career, and it wasn’t from a broker, it was from an asset manager: some of the greatest real estate deals are deals that never get done.
Craig Castelli:
We say the same thing.
Peter Billmeyer:
It can be the most aggressive deal. It can be all of these different things, but if it’s incongruent to the strategy of the business, that’s when you’re going to have some of the worst outcomes ever. And so those parts are set aside. We just bought a building on behalf of my brother and his group in Northwest Indiana. We closed in May. This is the holy grail. The private equity sponsor said, “You guys put up the capital, do the deal. We’ll give you a 10-plus-year lease.” But here’s what was so valuable, getting to tell the smart big-brother surgeon, “You’re going to put up this capital. They’re going to be paying that monthly rent.” And when you’re looking at a 36% IRR with, call it, a AAA credit tenant, I told them I’d put every nickel that they would let me. Of course, they didn’t let me in at all. But those are those deals that are so fun if you are skilled and know how to underwrite them and help tell the story. Because when you have 12 doctors that are partners, you better have somebody, and this is certainly not me, my partner, that can tell the story, answer every hard question and explain to them why putting X amount of dollars, real dollars, in on something like that. So it’s just, to me, all those stories are pieces of a puzzle that you just got to put together. And ultimately there should be a win-win. And if not, those are the deals that just don’t get done.
Craig Castelli:
Right. Well, sign me up for a deal like that any day.
Peter Billmeyer:
Right.
Craig Castelli:
So Peter, this has been a lot of fun and that’s probably a good place to leave this, but anybody watching or listening here wants to get in touch with you or learn more about Bespoke, where should they go?
Peter Billmeyer:
Bespokecre.com or find me on LinkedIn. You can call my cell, email, I will drop everything to answer questions. We’ve got a team of industrial, we’ve got a team of office. And even if this is cursory, even if it’s non-transactional and you just have questions, I’m always here. I love doing YPO, Vistage, EO, lunch and learns, just teaching: How do you manage your broker? I don’t need to be your broker, but you need to know the secrets, where the bodies are buried, to manage your broker. And also marry that with “real estate’s your down payment on culture.” That’s the other one. Very passionate about both. But we’re just happy to help anybody that is an entrepreneur. Somebody that risked everything to build these businesses deserves the very best. And that’s why it’s so fun watching what you’ve built and the impact you’ve had on all of your transactions and past clients.
Craig Castelli:
Well, I appreciate that. And I can tell anybody watching that he means what he says. He’s very sincere in that offer. It’s a no-strings-attached offer. So I’d encourage anybody to give Pete a call and take him up on this. Once again, man, a lot of fun. Thanks for joining. Thanks everyone for watching us here on The Close.
Peter Billmeyer:
Always great to see you. Thanks.
