

Caber Hill Advisors founder Craig Castelli sits down with corporate M&A attorney Mark Ryerson of Dickinson Wright to discuss practical dealmaking, current market conditions, and preparing a business for sale. They explore why productive negotiations require business-focused solutions, what founders should expect during due diligence, when to involve key employees, and how regulatory uncertainty affects transactions. Mark and Craig also share why early preparation can increase a company’s value, reduce transaction costs, and improve the likelihood of a successful exit.

Exploring the Art & Science of dealmaking
Welcome to The Close M&A Podcast with Caber Hill Advisors, where we bring you exclusive insights from M&A experts, business owners, and industry leaders navigating the complexities of buying and selling businesses. Hosted by Craig Castelli, this podcast demystifies the dealmaking process, shares success stories, and offers invaluable lessons for business owners and investors.
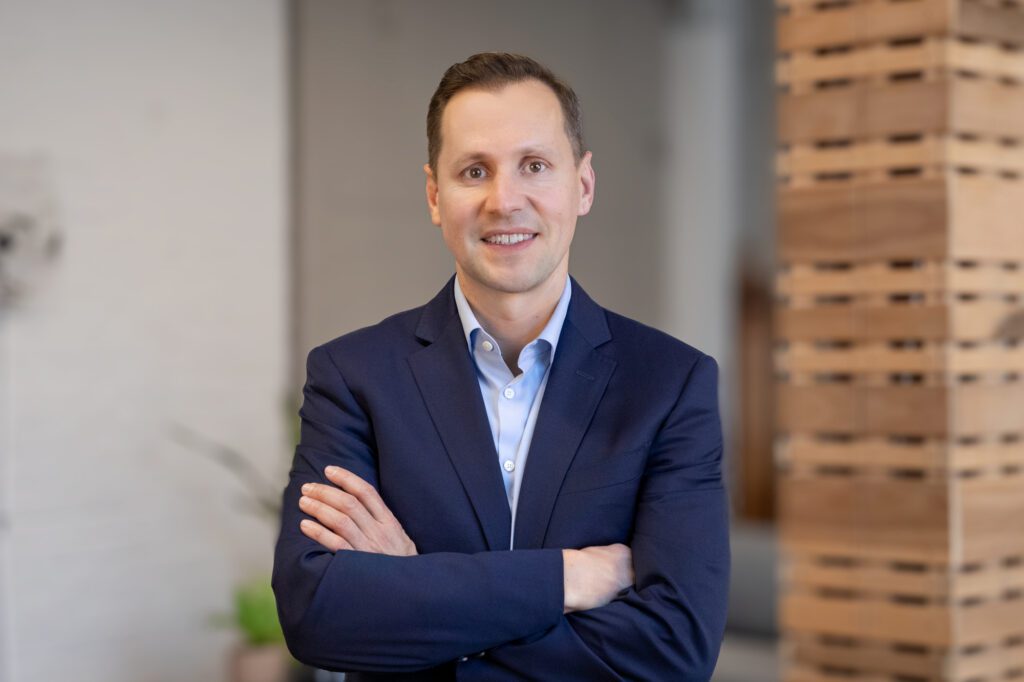
Craig Castelli, Founder & CEO of Caber Hill Advisors, is a trusted M&A expert with decades of experience advising business owners through successful transitions. Alongside a rotating roster of advisors, entrepreneurs, and investors, Craig brings engaging conversations that illuminate the world of middle-market M&A.
- ABOUT THE EPISODE
-

Caber Hill Advisors founder Craig Castelli sits down with corporate M&A attorney Mark Ryerson of Dickinson Wright to discuss practical dealmaking, current market conditions, and preparing a business for sale. They explore why productive negotiations require business-focused solutions, what founders should expect during due diligence, when to involve key employees, and how regulatory uncertainty affects transactions. Mark and Craig also share why early preparation can increase a company’s value, reduce transaction costs, and improve the likelihood of a successful exit.
- SUBSCRIBE
-
- ABOUT THE PODCAST
-
Exploring the Art & Science of dealmaking
Welcome to The Close M&A Podcast with Caber Hill Advisors, where we bring you exclusive insights from M&A experts, business owners, and industry leaders navigating the complexities of buying and selling businesses. Hosted by Craig Castelli, this podcast demystifies the dealmaking process, shares success stories, and offers invaluable lessons for business owners and investors.
- ABOUT THE HOST
-
Craig Castelli, Founder & CEO of Caber Hill Advisors, is a trusted M&A expert with decades of experience advising business owners through successful transitions. Alongside a rotating roster of advisors, entrepreneurs, and investors, Craig brings engaging conversations that illuminate the world of middle-market M&A.
- BE OUR NEXT GUEST
-
LISTEN
WATCH
READ
Craig Castelli:
Welcome to The Close M&A podcast with Caber Hill Advisors. I’m your host, Craig Castelli. Today my guest is Mark Ryerson. Mark is a member at Dickinson Wright where he co-chairs the corporate private equity and M&A practice. Mark is also our corporate attorney and we’ve worked together for years on a variety of projects. And Mark, I think where I want to start, what I’ve really come to appreciate about you and working with you, especially as it comes to negotiating various engagement letters and other Caber Hill contracts, is that you’re very commercial. Your goal is to strike a fair deal. And I just want to hear you set the table in your own words, what does it mean to be commercial to you and why is that important?
Mark Ryerson:
Yeah, absolutely. Well, I appreciate you having me on, so sincere thanks for that. So the difference between corporate attorneys and litigators is in theory for corporate attorneys, there’s always a business solution. It’s not a zero-sum game. Both parties can win. There’s a business way out of it. And so we always try to approach it from that direction. What’s our client trying to achieve? What’s the business solution here? And then the background is pertinent too, as you mentioned, what is market? What is commercial? What is the prevailing wisdom in the industry or for contractual terms? So we always approach it from that too. So we can ready client expectations, try to set expectations on the other side with this baseline of here’s what’s standard, here’s what’s market. It might not work in all circumstances, but at least approaching it from that as opposed to approaching it from a scorched earth platform.
My client has to dominate, my client has to take everything from a zero-sum game because that’s not productive to anybody. That results in transactions and deals not getting done.
Craig Castelli:
Yeah. We both find ourselves in positions where our clients come into the deal thinking that that is how they need to negotiate, thinking that the only way to achieve success is to win at the expense of the other side. Are there certain areas where you find, especially entrepreneurs who are going through some type of a deal for the first time, where they commonly want to dig in on a point that you have to educate them on why perhaps they’re not making the best decision to fight for something?
Mark Ryerson:
Yeah, I mean that’s an excellent point. So sometimes you’re never arguing with your client, but sometimes, like I said, you have to set expectations with your client about what is standard or what they might be able to achieve and identify for them what is unrealistic or what they’re not going to be able to achieve. And then you still take direction from your client there. If a client wants me to fight for X, Y, Z after we have a conversation that X, Y, Z is not standard, opposing counsel’s not going to give in on X, Y, Z. Hey, we’re a hired gun. We’ll still do that. We still advocate on behalf of our clients. But trying to understand what your client wants out of it, set expectations as to what’s market, what’s commercial, what might be achieved. Try to identify alternatives or different options for them that help them achieve their objectives without what they initially identified and then going to work to do it. And that’s what I love about you too, Craig. I mean, you’re sophisticated and you identify the points that you’re willing to negotiate on and you negotiate on those. You identify points that you’re not able to negotiate on, but you’re still open to alternatives to achieving the same thing with risk protection to your benefit, right?
Craig Castelli:
Yeah. I mean for us, it’s a decision of how badly do we want this? How interested are we in getting this contract signed? Usually that’s in the context of signing up a new client. And there are always lines that we’re not going to cross. Everybody has lines that they’re not going to cross, but I can lean on you and say, okay, what’s my risk here? Or what are some alternative pathways? And I think we do a good job of coming up with creative solutions together.
Mark Ryerson:
Yeah. And it’s giving what you can give on and it’s negotiating what you can’t give on.
Craig Castelli:
Right. And we had a recent one where I’ll try to keep this in vague terms, but the other side was pushing back on something that was pretty off market. I think it was in the indemnification. And you had a call with their attorney and their attorney said, look, I agree with you. I agree this isn’t market. The client is insisting on it. I’m not really sure what else I can do. And at least that level of transparency helped us make the decision as opposed to them digging in without any context and just appearing to fight for the sake of fighting. We ended up figuring out a solution in that case.
Mark Ryerson:
Yeah. And that’s a lot easier situation when somebody recognizes that they’re being unreasonable. And so you’re not stuck negotiating what’s market, you’re stuck negotiating solutions based on what they need. I mean, you and I had a different circumstance where something was very clearly market and we presented articles on it, we presented third-party resources on what was market, and they refused to acknowledge that it was market. So it’s like how do you negotiate against something when you don’t agree on the topic or the point?
Craig Castelli:
Right, right. So let’s stick on this investment banker engagement letter topic for a second. What are some things that an entrepreneur should know about what they’re signing and signing up for when they hired an investment banker?
Mark Ryerson:
Yeah, absolutely. So I mean, let’s take it from a perspective of engagement with you, but we do enough work in this area where we’re obviously not representing clients’ vis-a-vis engagement with you, but we represent clients’ vis-a-vis engagement with other investment bankers. So I think for both parties, it’s really relevant identifying what services are being provided. Are you doing a full-blown auction process? Are you not? Have you pre-identified buyers? Are you doing a SIM? Are you not doing a SIM? So really identifying both for your benefit and for your client’s benefit, what services you’re providing, what services you’re not providing, what they’re providing, et cetera. Another thing that we spend a lot of time on both representing you and representing our clients, vis-a-vis investment bankers, is the economics. And that’s largely a business decision, but it’s necessary for us to clearly outline them. So identifying whether there’s fee offsets, identifying the success fee, identifying different tiers for transactions and stuff like that. And then the third thing that I think is, again, the most important part from your perspective, also the most important part from a client’s perspective is that tail. The term and the tail. How long is this engagement? How does this engagement end run its course if it’s not successful? And what does the tail look like? And what does the tail encompass? Everybody that’s been talked to, people that sign NDAs, et cetera, et cetera. So those are the three highlights, and it doesn’t differ. Your perspective on it just differs based on what side you’re representing.
Craig Castelli:
Yeah, that makes sense. And I find myself oftentimes telling a potential client as we’re discussing just the structure of engagement letters, 99.9% of the time this is not going to apply, or we’ve never exercised this. I would really prefer not to give up the right in case we are in that 0.001% of the time where it doesn’t apply. But at the end of the day, we know that there are certain very important elements of it. And then there are certain things that are just the CYA language or things that you have told me, “Hey, Craig, everybody else is putting this in their engagement letters. You should have it in yours too, whether or not we’ve actually made use of it or not.”
Mark Ryerson:
Yeah. And to that point, I mean, you draft for that 0.1%, and that’s unfortunate. And we always try to take the position of not over-lawyering something or putting too much legalese in it, but you draft for the 0.1% and the 0.1% might never exist for you, but it exists for other people, which is why these provisions exist. And to your earlier point too, maybe the thing that we spend the most time redlining and going back and forth on is indemnification. But at the end of the day, with minor exceptions, we always find commonality and you’re always able to figure that out. It really comes down to the business terms, which is what you want as a lawyer. You don’t want legal to be impediment to getting the job done. If it’s not going to get done for some reason, you want it to be on the business terms.
Craig Castelli:
Yep. So enough about me and my engagement letters, that’s a pretty boring topic probably to most people watching here, even though I could talk to you about it for hours and ultimately do at times. You spend most of your time on actual M&A. And I think what’s interesting about your practice is you cover a fairly broad spectrum in terms of not just sector, but stage of the company because you do a lot of early stage work and then you also do a lot of more traditional middle market M&A. Do you find that the way you approach negotiating on behalf of an earlier stage company and structuring their series A or series B might be different than how you approach negotiating on behalf of a private equity firm who’s buying a company with 30 million of EBITDA? And obviously the documents and the deal structures themselves are different, but are there things that your radar is up for in one and not the other or things that you might want to fight harder for in one and not the other?
Mark Ryerson:
Yeah, absolutely. So I mean, excellent point. The first thing is, I hesitate to say sophistication, but on the early stage company side, you’re doing a ton of explanation and handholding and making sure that they appreciate the decisions that they’re making and the consequences of those decisions that you’re making. And on the M&A side, again, largely speaking, if it’s an acquirer, they’re going to be sophisticated, have done it before, know the integration process. Or if it’s a seller, while there’s concerns about trailing liabilities and indemnities and things like that, and you need to get the transaction right, they have less of a concern on a long-term go-forward situation. So you’re really kind of approaching it differently. On our startup clients, we’re always trying to position them for short-term and long-term success, which is difficult when they’re trying to hold onto as much as possible, but don’t have the funding to do it themselves or hold onto it. And then on the M&A side, you’re trying to get either a successful acquisition or a successful exit, and those metrics look a lot differently than setting up somebody for continued success and continued involvement on a go-forward basis.
Craig Castelli:
On the startup side of the equation, are you seeing certain stages where the fundraising environment is a little bit more favorable right now than others?
Mark Ryerson:
It ebbs and flows. We had a real problematic environment about a year ago where nothing was getting done from our perspective, and there was just a lot of capital in the marketplace not being deployed due to some uncertainty, economic environmental uncertainty. I think that’s largely phased out. Our clients that are raising early stage capital are largely raising from friends, family, angel investors. That seems to be progressing decently. Our clients that are raising Series B, Series C, et cetera, also seems to be going okay. Those two different pathways look drastically different. You’re using different investment vehicles for them. But again, knock on wood, I think it’s somewhat indicative of the public markets, even though there’s a whole bunch of possible recession indicators or economic uncertainty or political uncertainty. It still seems to be functioning. And whether that’s correct or not, I don’t know, but it’s somewhat surprising.
Craig Castelli:
So I was golfing the other day with a partner at a seed stage VC fund. So a lot of software, a lot of FinTech investments, seed to Series A. These days it’s been difficult for them to deploy capital because the big AI players are just gobbling everything up that is attractive in market, which tells me it’s probably a good time to be a founder in those spaces, perhaps better than it is to be an LP.
Mark Ryerson:
Yeah, I don’t disagree with you. I think there’s, again, a lot of, I hate using startup jargon, but dry powder in the marketplace, ready to be deployed. There’s funds that have made an extreme amount of money available for reinvestment. There’s strategic partners, like you said, in the AI space that are acquiring everything that they can acquire. I can name half a dozen clients that are perpetual entrepreneurs that are forming AI tangential or AI-focused companies just because of the short life cycle to maturity for sale. I mean, they realize that this isn’t a grow it for three years, five years. It’s a grow it for six months, nine months, and get out. It’s wild. It’s an interesting time.
Craig Castelli:
I wish I had that skillset.
Mark Ryerson:
I wish I had that patience. I wish I had that skillset. I wish I was that opposite of risk-averse. How’s the M&A environment for your clients?
Craig Castelli:
So I will say it’s good with an asterisk. The line I’ve been using, which I stole from someone else, is that the market’s very open, but it’s very unforgiving. What we saw a couple years ago, and you probably saw it too, was that when we came out of the pandemic, dry powder, to use that cliche term, had continued to amass and there was increasing pressure to deploy funds. And PE firms were buying less than perfect companies at perfect company prices because they had to put money to work. And that didn’t always work out well for them, surprise, surprise. And so what we’re finding now is that we’ve got the new regime with higher interest rates, a little bit more macro uncertainty than we had five years ago. Companies not performing perhaps as expected or lessons learned from overpaying for certain companies. And so the diligence is heightened. Lender scrutiny is through the roof. And so there’s just less forgiveness for imperfect businesses. And if you’re not really buttoned up going to market, you’re subject to a retrade, you’re subject to a broken deal, but deals are still getting done. And when you have a truly uniquely differentiated asset, not unique because you think you provide better customer service, but something actually unique and differentiated about your go-to-market strategy, if you have a proven growth engine, if you have the right type of sticky customer relationships and you don’t have key reimbursement risk or key customer concentration, you are still seeing a lot of interest from the investment community. And those deals are getting done. And I’ll circle back maybe one last time to that phrase dry powder. Fundraising hasn’t stopped on the PE side, and funds are starting to get dated. And I know a lot of PE partners who didn’t meet their capital deployment goals in 2025. And so at some point that levy has to break. Either they won’t be able to continue to raise the funds that they have raised in the past, and we’ll just see overall fundraising levels come down, or they’ll continue to deploy capital, they’ll continue to raise funds. That cycle will repeat itself. They will probably more likely than not figure out how to make money on these investments and forward we’ll all go.
Mark Ryerson:
Yeah. Yeah. No, it’s a really great way to frame it. And we’ve seen the exact same things that you’ve seen. Increased due diligence, which again, from a buyer perspective, not a bad thing. Increased lender scrutiny, which again, from a macro banking perspective, not a bad thing. It’s just a little bit more difficult on seller side.
Craig Castelli:
I think where the PE firms have room for improvement is some recognition that the seller on the other side of the table, if they’re a founder, doesn’t understand why they’re asking the same question for the third or fourth time. Doesn’t understand why all of this diligence is necessary, and they don’t explain it to them. They don’t put it in terms that they can understand. What we try to help our clients do in a sale process is go in eyes wide open and think about their own business the way a buyer would look at it. But even then, you can’t help but reach a certain point of frustration as diligence just drags on and on and on. Some of it’s gamesmanship. Some of it’s just a poor job of framing it by the buy side as to, look, we are doing this because our lender is making us do it. Our lender is doing it because two years ago they had an investment and this is what happened and once burnt twice shy type of approach. Like it or not, at least you understand, okay, there’s a reason behind this. You’re not just trying to annoy me. You’re not just trying to betray me. You are beholden to somebody else or you are learning from a past mistake. And I don’t know why some of those simple explanations can’t be given, but sometimes pulling teeth to get that out of a VP at a PE firm.
Mark Ryerson:
No, I agree. And two things that I think PE firms oftentimes lose sight of or oftentimes forget to take into account is sellers trying to do their day-to-day work while running this sale process, which is exhausting and extremely time-consuming and extremely detail specific. A lot of times seller does not have everybody under the tent. So they’re trying to do this with the C-suite and board, or they’re trying to do this with just a few people, and that compounds a problem of how difficult it is. And then a lot of times in some of the markets that you and I operate in, you have sellers that have never gone through this type of process or are super great at their business, but might not have some financial acumen. And again, they don’t understand, like you said, why it’s been asked six ways from Sunday.
Craig Castelli:
I’ll give my answer, but I’ll ask you this first. What do you tell a CEO or a founder who doesn’t want to bring the rest of the C-suite under the tent?
Mark Ryerson:
You’re making it harder on yourself, right? Yeah. I mean, the only person paying the price here is you. So we try to encourage our clients to be realistic about the diligence that they’re going to be facing, about who in the organization has answers to some of these esoteric or historical questions, who has access to the information that a buyer’s going to need. We just had a situation not long ago where super large transaction and represented seller-seller didn’t bring anybody from HR in on it. And so buyers asking for employee listings, salaries, hiring information, and we can’t produce any of this information till the last possible minute. So we encourage CEOs to be realistic about the process, realize that they’re going to need help, and identify or mitigate risk on what they’re worried about. Talk to buyer about what a stay bonus looks like. Talk to them about when you need them through what portion of the transaction to stay. Try to overcome some of those fears. Put in place ironclad NDAs with your employees that you’re bringing or the intent and that you’re worried about. Ways that we can mitigate founder, CEO risk on who they’re involving in the process.
Craig Castelli:
Yeah, I think that it’s completely natural to have concern about letting anybody know that you’re entertaining this. But there’s a difference between entertaining a deal and signing an LOI and agreeing to go forward with a deal. And what I think the average CEO misses is that they actually look worse if they’re trying to do it all themselves. I mean, at the end of the day in most businesses, a lot of what’s being purchased is the team, is the people. It’s their output and their capability that drives the value in the business, and you need to demonstrate that through the sale process. So forget the fact that you’re going to drive yourself crazy and increase your stress to unnecessary levels by trying to do it all yourself. You’re actually more than likely going to drive a better outcome if you have the key people responsible for these different functional areas under the tent at the appropriate time and in the appropriate conversations. They don’t need to be privy to every single aspect of the deal. But to some of the things you mentioned, getting them under NDA, if that’s not already something that’s part of just their overall employment package, perhaps offering them some type of incentive tied to the deal. It may be a natural function of the deal itself if there’s some sort of management incentive pool that’s created that they get to participate in, but everybody likes cash. Sit them down, say, “Hey, look, you’ve been fundamental to growing this business. We’re entertaining an investment, we’re entertaining a sale. I’d like to thank you for what you’ve done here. I’m going to need your help, but I’m also going to reward you. What is meaningful to them may be a drop in the bucket to you in the context of the overall purchase price, and it will make your path to closing so much smoother.”
Mark Ryerson:
Yeah. And going back to that original point too, a lot of times diligence drags on, a lot of times sellers get frustrated with diligence and things are asked three different ways is because the information being communicated is incomplete or partial or not correct or non-responsive. And that’s a function of not having the right people participating in the process, right?
Craig Castelli:
Right. Yeah, you’re absolutely right. It is the fact that there’s usually some level of lack of data or lack of data clarity in smaller businesses that is just understood and accepted. And then there’s a business that reaches a certain size and scale where there’s a fundamental expectation that you can provide this, you can answer this, you can articulate this. But a CEO shouldn’t have to do all of that. They frankly shouldn’t be the best to do all of that across all functional areas and bringing your team in and demonstrating that you have this competent, capable team really smooths over a lot of these speed bumps.
Mark Ryerson:
Agreed. Agree.
Craig Castelli:
So I want to shift gears a little bit and get back to some of the sector level M&A talk, because I know you spent a lot of time with banks and financial institutions and M&A in those sectors has been a core of your personal practice for a long time. And what I’ve heard is that there’s been some loosening of regulation around those deals that theoretically makes it easier to get regulatory approval to close M&A in that space. I have a feeling you’re going to tell me that that is true on paper and less so on practice. But rather than putting words in your mouth, talk about that sector and what’s going on these days.
Mark Ryerson:
Yeah, absolutely. So half my practice is M&A. Half my practice is what we call private capital markets. So companies raising capital or investors investing in companies raising capital. On the M&A side, a good chunk of that M&A is industry agnostic. A good chunk of that M&A is, like you said, financial institution, bank M&A. And I think this is probably largely true across other regulated sectors, not just banks and financial institutions. But this administration, generally speaking, has given the directive that they want transactions to be approved, that they want transactions to be approved on a faster basis, that they want less roadblocks to transactions being approved. So all fine and good, that’s the general directive that we understand coming from this administration. The problem with that is that coupled with that, you’ve had an extraordinary reduction in headcount across governmental agencies over the past year, two years. You’ve also had a culture of uncertainty. So we’re seeing, yes, there’s this directive to approve it without a lot of roadblocks or on a quicker basis. We’re also seeing a lot of agencies being short-staffed and don’t have the people to approve it. And we’re seeing that the people that are in a position to approve it, to the extent that they might be overworked, they also might be concerned about continuation of their job, what they’re actually supposed to do, concern about approving something that they’re not. So there’s this culture of uncertainty. So on the whole, regulatory approval’s always a difficult and time-consuming process. And it’s varying widely, wildly regulator to regulator, varying wildly transaction to transaction. We’re seeing some regulators approving record time. We’re seeing some take longer than normal. Overall, I think it largely evens out to where we were in the prior administration. There’s just more uncertainty. We can’t tell clients with as much definitiveness what it’s going to look like.
Craig Castelli:
It seems like there are two objectives really conflicting with each other head-on, the headcount reduction with the reduction in red tape, it’s kind of hard for one to win there.
Mark Ryerson:
Yeah, you hit the nail on the head, right? Yes, it would be much easier if people were fully staffed, had secure job prospects or consistent direction on what was going on from all levels plus a diminished or reduced timeframe and everything, again, in theory would work smoothly.
Craig Castelli:
Yeah. We don’t do the financial institution work, so I can’t comment on that. But as you know, a huge part of our practice is healthcare, which certain sectors can also be very subject to various types of what we call stroke of the pen risk. If CMS decides to change reimbursement or perhaps put a moratorium on new Medicare billing registrations, you basically can’t get a deal done. And that’s hitting certain sectors like home health and hospice right now squarely between the eyes. And you assume that there’s a specific problem that they’re focused on that they’re trying to address, that once addressed, everybody will get back to business as usual, but you reach these periods where your hands are just tied.
Mark Ryerson:
Yeah, absolutely. So I mean, you’ve got regulatory risk, you have consummation risk, and you have the risk of marketplace changing at the drop of a hat. I mean, how do you prepare sellers for that? How do you account for that?
Craig Castelli:
That is, like you just said, company by company, sector by sector. Part of it is just having a realistic understanding of what you can and can’t control. I think the bigger aspect is making sure you get your compliance docs in a row years in advance of selling. So the specific issues, play gain, home health, like I just said, is that you can’t get a new provider number with Medicare for home health and hospice agencies right now. So what is the solution there? The solution is that you buy stock in the company and then you just take over that provider number and you don’t have to worry about a new registration. Well, who wants to buy stock when you also have an administration that is rapidly increasing enforcement of any sort of fraud, waste and abuse action? And as part of that, you’re seeing massive increase in the number of audits. And an audit, even if you come out on the right side of it, it is costly, it is distracting, and it absolutely slows down your growth. So if I’m in a business that is subject to this type of regulation, I’m going to think I want to make sure I have at least three years of a very, very clean trail. It probably starts with calling you and saying, okay, what do I need to do? What type of records do I need to have? Can you and your firm come in and do some sort of audit on how I’m operating right now so that when I go to market, I can show that I have these clean records? We talk for years about the value of quality of earnings and why that helps a seller when they go to market present the best numbers, the cleanest numbers, numbers that align with how a buyer’s going to look at them. And I think the next trend in these heavily regulated industries will be to move towards auditing in other aspects of the business, whether it’s billing and coding, compliance. I’m sure there’s an equivalent in the financial institution side of things. The PE firms do that before they sell their portfolio companies, and founders need to start taking a real hard look at doing that in their own businesses.
Mark Ryerson:
I mean, excellent point. I think both of our professions are similarly situated in that it helps us maximize efficiency and make the process the best possible process for the seller. And it helps you maximize price if we have a substantial heads-up as to what this exit looks like down the road. I’m looking to go to market in a year. What do I need to do now to prepare myself for going to market then? Not, I need to sell tomorrow.
Craig Castelli:
Right. Yeah. Look, at the end of the day, I’m running a business here and we need to sell companies in order to make money. And when somebody calls me up and says, “Hey, I’m ready to go to market tomorrow and I was told to call you,” I love that and we’re ready to jump right in. But there absolutely is value to getting that call a year in advance and spending some time with that company and that founder so we can really dig into the business, help them clean up at least the low-hanging fruit, and also just help align with them on their own personal goals for the deal to make sure that everything lines up exactly the way they want it to. Yep.
Mark Ryerson:
Agreed.
Craig Castelli:
So Mark, this has been a lot of fun. I mean, I’ll ask you one last question, but before we hop. I mean, if there’s one lasting piece of advice you’d give to the business owner community out there who’s watching this, who may be preparing to go to market in the next year or two, what would it be?
Mark Ryerson:
Oh, excellent question. I think it’s putting in the legwork ahead of doing so to understand what the process looks like. What is it going to look like for me from a timing perspective? What does a good exit look like for me? What does a not so good exit look like for me? Understanding what this process entails and then putting in the legwork, like you said, to get their house in order, to anticipate what a buyer’s going to look at, to clean up low-hanging fruit, address minor problems, clean up systems, clean up processes, clean up records, put themselves in the best possible situation for success by understanding the process and preparing for it.
Craig Castelli:
Yeah. Why would you act impulsively on what is likely going to be the biggest financial decision you make in your entire life? Yet we both see so many people that do.
Mark Ryerson:
Yeah. And from your perspective, again, you’re going to be in a better position to increase value if that is the case. And from my perspective, we’re going to be in a lot better position to spend less on fees, less time, less money, less effort, if that is the case. It’s twofold. You’re going to increase your purchase price, you’re going to decrease your transaction expenses if you take those steps.
Craig Castelli:
Right. I mean, if that’s not a value proposition worth listening to, I don’t know what is.
Mark Ryerson:
Yeah. And again, not to add another thing, but it’s not waiting until you have to go to market. It’s doing strategic planning on a regular basis. What’s the market look like now? What does my business look like now? What does it look like in three months? And I’m sure that’s something that you deal with your clients on and educating them on that and when the best time to pull the ripcord is.
Craig Castelli:
Yeah. I mean, one thing I find myself saying ad nauseum is exit strategy is really just good business strategy. If you have a business that is primed for sale, it’s probably easier and more fun to run that business. It’s probably a lot more profitable. And so why wouldn’t you want that even if you think an exit is 10 to 20 years in the future?
Mark Ryerson:
Yeah. Yep. Agreed.
Craig Castelli:
All right. Well, Mark, again, appreciate you joining here. If somebody wants to learn more about Dickinson Wright or connect with you, where should they go?
Mark Ryerson:
You can go to our website, dickinson-wright.com. You can contact me, (312) 377-7863. You can email me. I take texts, whatever I can do to connect.
Craig Castelli:
He truly does work twenty four seven. Whether that’s a good thing or a bad thing, I’ll let others judge. But Mark, once again, appreciate it. Thanks everybody for watching us on The Close.
Mark Ryerson:
All right. Thank you so much for having me on, Craig. I appreciate it.
